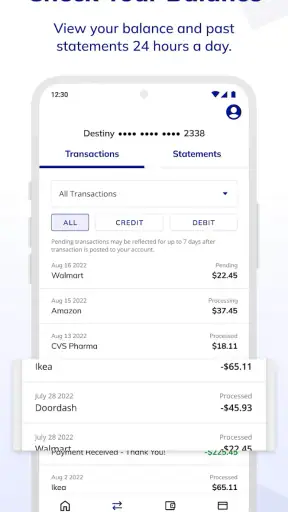
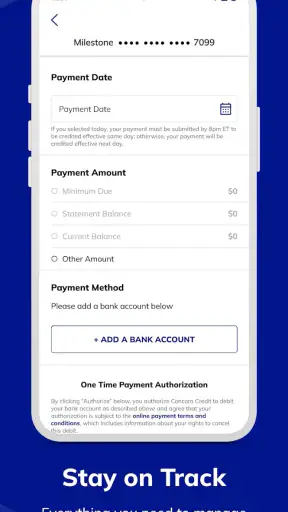
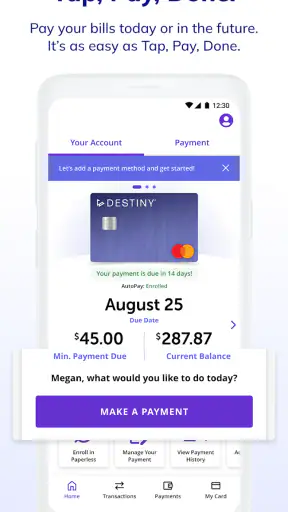
Managing a credit account from a phone sounds simple, but the right app can make a real difference when you need to check a balance, review activity, or handle an account away from a computer. I spent time looking at Concora Credit as a mobile finance tool, and my impression is that it is most useful for people who already have an account with Concora Credit and want a more convenient way to keep an eye on it. It is not trying to replace a full banking app, a budgeting platform, or a general-purpose money manager.
The app is free to download, carries an Everyone age rating, and is developed by Concora Credit. Its purpose is deliberately narrow: it gives customers a mobile place to manage their account or accounts. That focus is both its main strength and the first thing I would consider before installing it. If your financial life is centered on a Concora Credit account, the app can remove small but repeated bits of friction. If you are looking for a complete picture of spending, savings, bills, and credit across several institutions, you will probably need something broader.
What I would look at before choosing it
My first decision criterion is eligibility in practical terms: do you already use Concora Credit? This is not an app I would download simply because I wanted a general finance dashboard. Its value comes from the relationship between the customer and the developer. Without an account to manage, there is little reason to expect it to become a useful everyday money tool.
The second criterion is the task you want to complete. A focused account app makes sense when your priority is checking account information quickly, reviewing recent activity, or keeping routine account management close at hand. It is less suitable when the main goal is building a monthly budget, combining accounts from different providers, tracking investments, or analyzing spending categories in depth.
I also pay attention to how much confidence an app inspires during ordinary use. Finance apps are not judged only by appearance. I want to find information without hesitation, understand what I am looking at, and avoid unnecessary trips through menus. Concora Credit has a modest average rating of 3.4 from around 3.5 thousand ratings, alongside roughly 1.7 thousand written reviews. That tells me the experience is useful for many customers but not universally smooth, so I would approach it as a practical account companion rather than a polished all-in-one financial command center.
Its reach is still significant: the app has passed one million installs. That does not guarantee that every customer will enjoy the same experience, but it does show that this is an established mobile route for Concora Credit account management rather than an obscure experiment. The current release is version 3.0.17, and the app was released on June 21, 2023. Those details matter mainly because users should keep the installed version current when dealing with financial information.
The everyday problem it solves
Imagine that I am away from home and want to check an account before making a purchase. I do not want to open a laptop, search through old messages, or wait until I can remember the details later. A dedicated account app gives me a direct place to look. Even a short check can be worthwhile if it helps me confirm recent activity or understand where the account stands before I make another decision.
That convenience becomes more valuable when checking an account is a repeated habit rather than a one-time task. I might review the account after a purchase, before planning a payment, or during a weekly money check-in. The important insight is that the app works best as part of a routine. It is not a replacement for financial planning; it is a quick access point that can help me stay aware of one particular credit relationship.
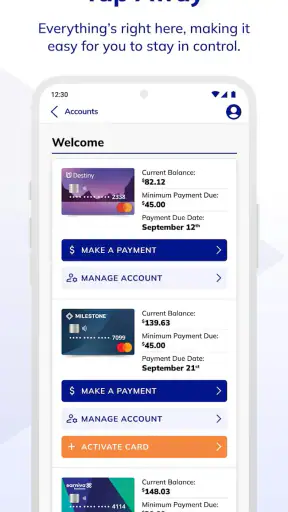
For households with more than one relevant account, the wording that Concora Credit uses for managing account or accounts is worth noticing. A user with multiple accounts should think about whether the app presents them in a way that feels clear enough for regular checking. Keeping separate account information mentally organized can be harder than simply opening an app, especially when balances and activity belong to different accounts. I would make the first login a deliberate setup session rather than assuming everything will immediately feel obvious.
Where the focused approach works well
The strongest part of Concora Credit is its narrow purpose. I do not have to sort through investment charts, savings goals, insurance tools, or unrelated banking features to reach the account I actually want to see. For an existing customer, that can make the app feel more direct than a general financial service that tries to cover every possible money task.
I also like the idea of separating account management from broader budgeting. A budgeting app may be excellent for seeing household trends, but it can be too much when I only need to check one credit account. Concora Credit is easier to justify when the question is specific: what is happening with this account, and what do I need to do about it? A smaller tool can be more useful than a larger one when it matches the question.
Another practical advantage is reduced dependence on a desktop browser. Mobile access matters for people who check finances in short moments: during a lunch break, while organizing a shopping list, or after receiving a transaction notification. I would not use those moments for a full financial review, but they are suitable for a quick account check. That distinction helps keep expectations realistic.
The free price also lowers the barrier to trying it. There is no separate purchase to make before seeing whether the mobile experience fits my habits. Still, “free” describes access to the app itself, not the financial terms of any account managed through it. I would never treat a free download as evidence that borrowing is inexpensive or that account costs have changed. The app is a management tool, not a discount on credit.
Small habits that make the app more useful
I would use the app alongside a simple personal record rather than relying on memory. After reviewing account activity, I could note the important information in my normal budget or calendar. This creates a useful division of labor: Concora Credit remains the place to inspect the account, while my separate planning method handles household decisions. That approach is especially helpful if I use several financial providers.
I would also avoid opening the app only when something feels wrong. A short, regular review makes unusual activity easier to notice because I have a clearer sense of what normally appears. This is not a substitute for reading account communications carefully, but it is a sensible workflow for turning a mobile account tool into a monitoring habit.
For multiple accounts, I would check each one intentionally rather than assuming that looking at the first screen tells the whole story. A useful routine could be to review the account selector or account list first, then inspect the relevant activity, and only afterward move to the next account. The benefit is not a hidden feature; it is a simple way to reduce the risk of confusing one account with another.
Where other types of apps may fit better
Concora Credit is not automatically the best option just because it is the official app connected to a credit provider. Official access is valuable, but the best tool depends on the job. If I want to see balances from a bank, a card issuer, and a savings provider together, a broader financial aggregator may be more convenient. I would accept that wider view only after considering whether I am comfortable connecting multiple accounts to another service.
If my main challenge is overspending, I would look toward a dedicated budgeting app instead. Budgeting tools are designed around categories, targets, recurring expenses, and longer-term patterns. Concora Credit can help me manage the account it represents, but I would not expect it to explain my entire monthly cash flow or show whether my spending is balanced across all areas of life.
A bank’s main mobile app may also be a better home base for someone whose finances are already concentrated there. A banking app can make more sense when I need transfers, deposits, savings management, and account servicing in one place. Concora Credit remains preferable when the specific Concora Credit relationship is the account I need to inspect, but it may feel like one extra app if my bank already gives me the complete view I need.
There is also a case for using a desktop browser instead of a mobile app. Someone who manages finances only once a month, prefers a larger screen, or wants to print and compare records may not gain much from installing Concora Credit. The phone experience is most compelling for frequent, short checks. For occasional administration, a browser-based routine may be perfectly adequate.
People who need detailed credit education or broader debt planning should be careful about what they expect from a provider-specific account app. A credit account manager can be useful for staying connected to one account, but it is not the same as a debt payoff planner or a personal finance coaching service. If I were comparing repayment strategies across several debts, I would want a tool designed for that wider decision rather than forcing one account app to do the work.
What switching to mobile management involves
The cost of switching is not mainly financial because the app is free. The real cost is time and habit. I need to install it, sign in, become familiar with the account layout, and decide whether it is easier than my current method. For someone already using the Concora Credit website, the change may be small. For someone who keeps paper notes or checks infrequently, the benefit may not justify changing routines.
I would begin with a low-risk test: open the app, identify the account or accounts I expect to manage, and see whether the information is organized clearly enough for a normal check. I would not make the first session the moment I need to solve an urgent account issue. Learning the navigation beforehand gives me a better chance of recognizing whether the app is genuinely convenient.
It is also sensible to keep another access method available while forming a new routine. If the app does not present something in the way I expect, I do not want to be locked into a single channel for an important account task. This is not a criticism unique to Concora Credit; it is a good practice with any finance app. Mobile convenience should add an option, not remove all alternatives.
Privacy and device habits deserve attention too. Since this is a finance app, I would use a screen lock on the phone and avoid leaving an account session open where someone else could access it. I would also install updates through the normal app store process and be cautious with messages that ask me to enter account information outside the app. These are ordinary safeguards, but they matter more than cosmetic differences between finance apps.
The minimum operating system requirement is Android 7.1, which makes the app accessible to a broad range of Android users with older devices. Even so, compatibility on paper is not the same as comfort in daily use. On an older phone, I would pay attention to loading behavior, keyboard responsiveness, and whether moving between account screens feels dependable. A finance app should be judged by confidence and clarity, not merely by whether it launches.
Who should use it and who should skip it
I would recommend Concora Credit first to an existing customer who wants a direct mobile way to manage a Concora Credit account. It is a reasonable fit for someone who checks account activity regularly, prefers using a phone to a browser, and does not need a unified dashboard for every financial provider. The free download makes trying it straightforward, and the Everyone rating means it is presented as suitable for a general audience.
I would be more cautious about recommending it to a person who wants a complete personal finance system. If you need detailed budgets, investment tracking, shared household planning, or a consolidated view across institutions, a broader app will likely save you time. You may still keep Concora Credit for account-specific checks, but it should not be the only tool you expect to answer every financial question.
I would also skip it if I do not have a Concora Credit account. Installing a provider-specific app without a matching account relationship is unlikely to improve my financial routine. In that situation, a bank app, budgeting tool, or neutral account aggregator would be a more logical starting point.
For users who are frustrated by mobile apps in general, the rating of 3.4 is a useful warning to keep expectations measured. The app has enough adoption to be worth considering, but I would not assume that every screen or workflow will match the smoothness of a premium budgeting product. My recommendation would depend on whether the focused access solves a real problem, not on expecting a perfect interface.
My recommendation after weighing the alternatives
My overall view is that Concora Credit is a sensible companion for the specific account it is built to manage. I would install it if I were already a Concora Credit customer and wanted quick mobile access to account information and routine management. The focused design is more of a benefit than a weakness when I need one clear destination instead of a crowded financial dashboard.
I would not present it as a replacement for a bank app, a budgeting service, or a debt-planning tool. Those alternatives serve different purposes, and choosing one depends on whether I need account access, a complete financial overview, or help making longer-term decisions. The best setup may involve Concora Credit for provider-specific management and another tool for the wider picture.
The most practical way to decide is to test it against one real routine: checking an account after activity, reviewing several accounts in sequence, or confirming information before planning a payment. If that task becomes faster and clearer, the app earns a place on the phone. If I still need a browser or another service for every meaningful question, then the extra app may not be worth keeping.
With over one million installs and a free entry point, it is easy to try, but the average rating shows why I would judge it personally rather than relying on popularity alone. My final recommendation is conditional but positive: use it as a focused Concora Credit account manager, keep your broader budgeting method separate, and choose a different category of app when your needs extend beyond that single provider relationship. The right reason to install it is convenience for an existing account, not the promise of complete financial management.


